How to Balance Family Expenses with Ease
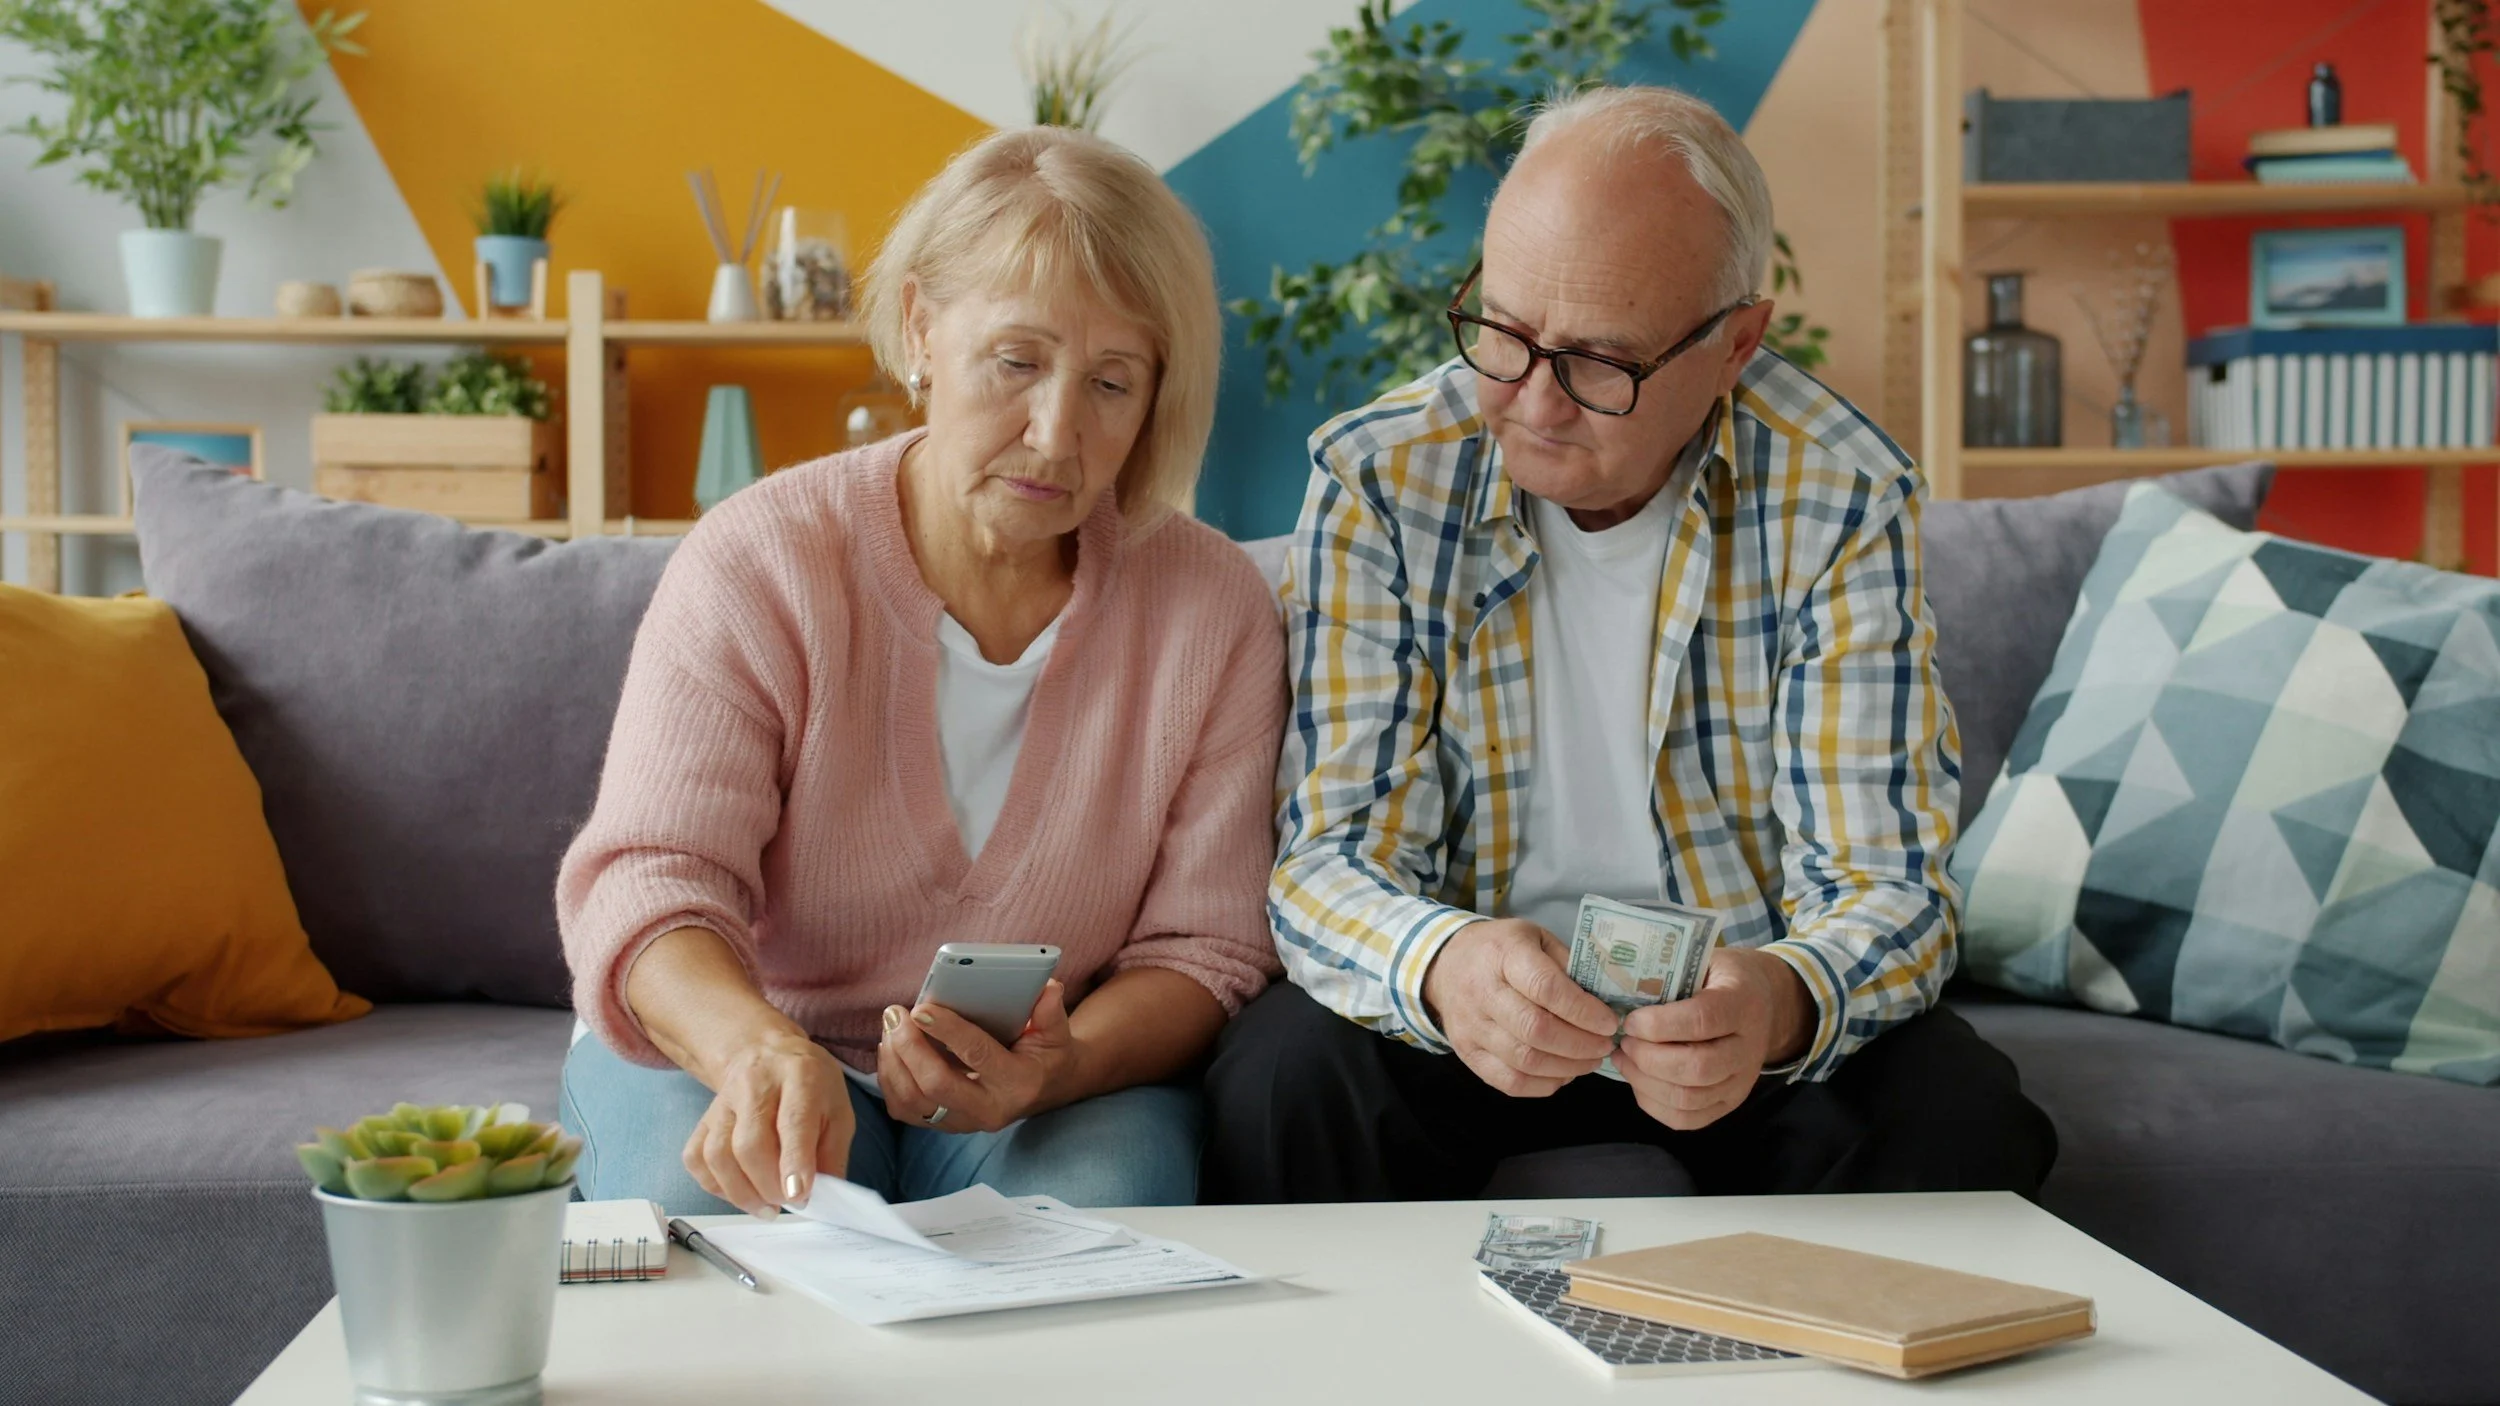
Household money rarely goes sideways in one dramatic moment. It leaks. A bigger grocery run here, a sports registration there, a dental bill nobody budgeted for, and by the third week of the month the account looks thinner than the plan promised. Families who seem calm about money are not always earning more than their neighbors. They have usually built a system that absorbs surprises without turning every Tuesday into an argument about spending.
Balance does not require a spreadsheet with forty tabs or a solemn vow to quit buying coffee. It requires a few decisions made once, written down somewhere you will actually look, and revisited two or three times a year. The Federal Reserve, which surveys how households handle income, expenses, and financial shocks, has found year after year that the difference between stress and steadiness often comes down to whether any cushion exists at all.
So here is a sequence that works for ordinary families with ordinary paychecks: see the real numbers, rank the bills before the month starts, build a buffer that does the worrying for you, and trim the handful of categories that quietly eat the most. No windfall needed.
Start With an Honest Picture of the Money
Pull the last three months of bank and card statements and sort every line into three buckets: fixed, variable, and irregular. Fixed is rent or mortgage, insurance premiums, the phone plan. Variable is food, gas, and the things that flex with how the month goes. Irregular is where most budgets go to die, because nobody plans for tires, orthodontics, or a birthday party in April.
Add the irregular bucket up for the year, divide by twelve, and treat that figure as a real monthly bill. Suddenly the budget stops lying to you. Most families discover their true cost of living sits a few hundred dollars above what they assumed, which explains the slow drift onto the credit card every spring and every holiday season.
Rank the Bills Before the Month Starts
Priority beats discipline. Decide in advance which obligations get paid first and automate them on payday, so housing, utilities, food, transportation, and insurance clear before anything optional touches the account. Federal financial education guidance on spending suggests setting a maximum for each week or month and then holding that ceiling, which sounds obvious until you notice how rarely households actually name a number.
The ranking matters most in a tight month. When income arrives late or a paycheck shrinks, a family with a written order of operations does not have to negotiate under pressure. They already know the roof, the lights, the groceries, and the coverage that protects the car come first, and that the streaming bundle can wait.
Build a Cushion That Does the Worrying for You
An emergency fund is not a moral achievement, it is a shock absorber. Start embarrassingly small if you have to, because fifty dollars a paycheck into a separate account still becomes thirteen hundred in a year, and the first milestone worth chasing is one month of essential expenses rather than the mythical six. Keep it somewhere boring and slightly inconvenient, away from the debit card.
Then protect the cushion with a rule: it covers the unexpected, not the merely unbudgeted. A blown water heater qualifies. Concert tickets do not. Families who hold that line stop reaching for high-interest credit when the dryer dies, and the interest they avoid is effectively a raise nobody had to ask for.
Trim the Big Categories, Not the Small Joys
Cutting lattes is theater. The money lives in four places: groceries, transportation, healthcare, and insurance. Plan meals around a short rotation and shop once rather than four times, combine errands into a single trip, use in-network providers and ask what a visit will cost before you sit in the chair, and review coverage on a schedule instead of letting it renew on autopilot.
Insurance deserves its own hour. Premiums drift upward quietly, and a household that has not compared quotes in three years is often paying for a risk profile it no longer has. Along the Grand Strand, drivers reviewing auto insurance Myrtle Beach sc options frequently find room to raise a deductible, bundle two policies, or drop a rider that stopped making sense once the car got older. Vacations respond to the same planning instinct, and mapping transport and lodging costs by destination, the way this guide to family travel logistics does, keeps one good week from becoming next year's balance.
Keeping the System Alive
Balance is not a state you reach, it is a habit you maintain. Put a thirty-minute review on the calendar every quarter and check three things: whether the irregular bucket still matches reality, whether the cushion grew, and whether any recurring charge has outlived its usefulness.
Bring everyone old enough to understand into the conversation, because a plan one adult guards in secret tends to collapse the first time someone else spends freely. Kids who hear why a trip is happening in May rather than July learn something durable. And a household that knows its own numbers makes faster, calmer decisions than one that merely hopes the month works out.